

Review all prior ONON research and portfolio changes on the TSOH website
From “On Holdings: Maintaining Pace” (July 2026):
“Mr. Market has some concerns about the sustainability of their current financial trajectory. Personally, I am somewhat less pessimistic about On than I think this rating implies. I see a premium athletic brand that etched out a unique position in the industry, at least at its current size… If I walk away from [On’s 2026 Investor Day] with more appreciation for where this business can go over the next five to ten years, I will be open to changing my conclusion.”
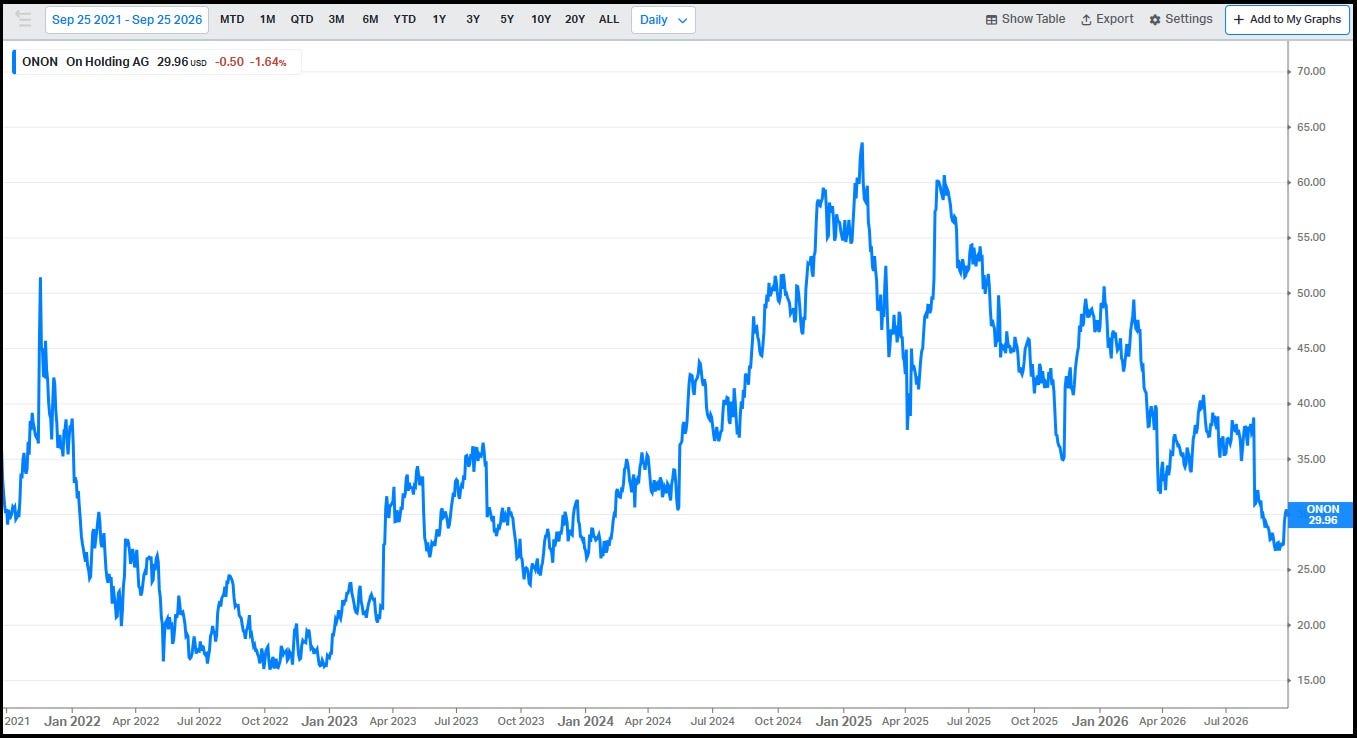
The Investor Day in question was held last week in Zurich, with the company setting medium-term financial targets through FY29, announcing their first share repurchase authorization, and detailing their plans to expand into golf and soccer (welcome aboard Mbappé). For a stock that has spent most of 2026 heading in the wrong direction, the >10% pop in response was a notable change in direction; with that said, it’s still down ~35% year to date.
The Mbappé signing is a fitting place to start, because I think it captures the broader strategic vision for On. As management noted at the Investor Day, “We are entering because at the premium end of the sport there is still space left open for radical innovation on the pitch... A few incumbents own the architecture of the category, and they compete head-to-head. We will play a different game… Our innovation engine has given us an entry ticket nobody else holds. I’m quoting Sydney Schertenleib – ‘I’ve never felt the ball like this before’. That’s what Sydney said after her very first practice in an early concept of our upcoming performance football boot. This is the disruptive power of LightSpray. On a football boot, LightSpray does something that no other boot has done: it puts almost nothing between the foot and the ball.”
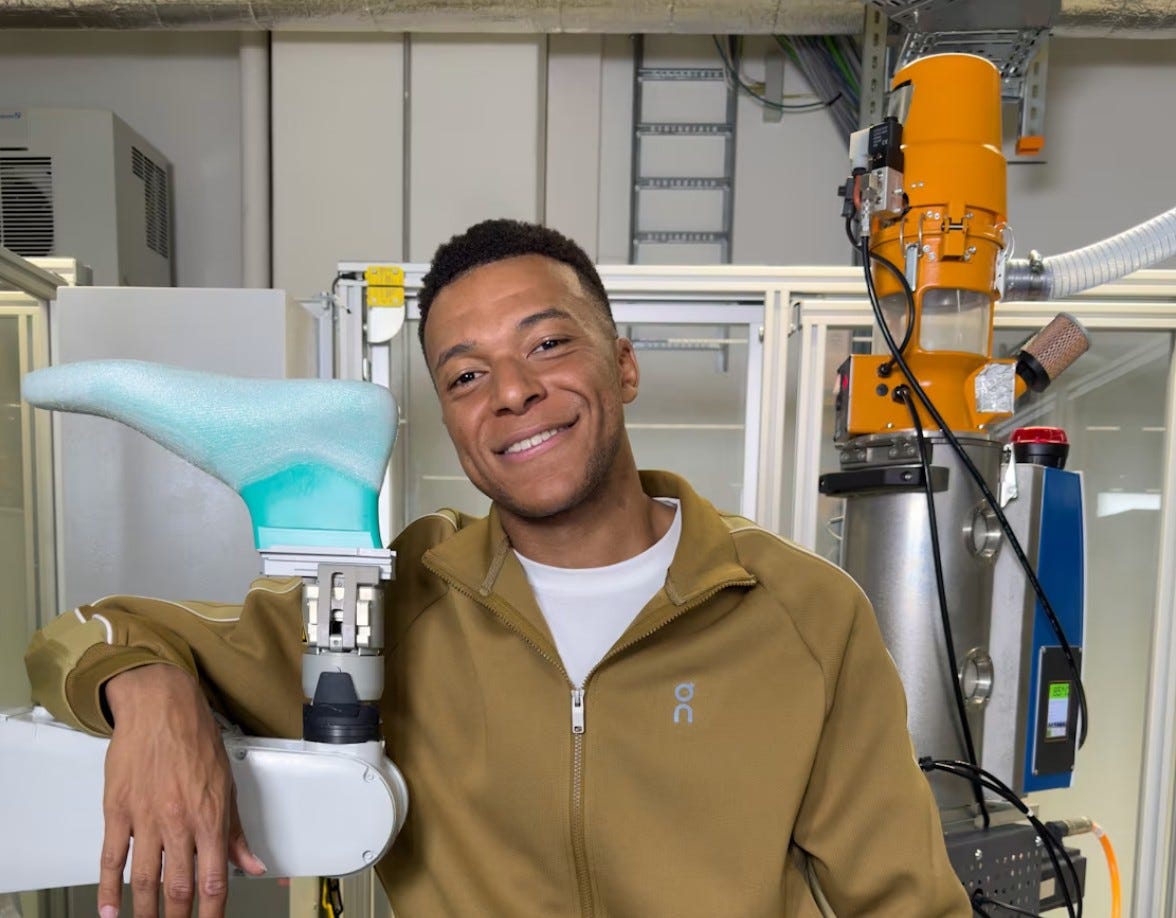
It’s clear that On’s initial efforts in soccer will be focused on top of the line premium cleats with a LightSpray upper (they currently offer two different styles of LightSpray men’s shoes – the Cloudmonster 3 Hyper for $280 and the Cloudboom Strike 2 for $310). They have no interest in competing with lower end (~$100) soccer cleats sold by Nike and Adidas, let alone the endless list of brands sold through sites like Amazon for even less. On enters the market with a clear focus on selling to a select group of soccer players who are willing to pay a premium for the highest quality boot they can make.
This should sound familiar, because it mirrors what they’ve done in running, tennis, etc. As co-founder Caspar Coppetti has said about On’s early days, “Passionate runners were investing more into their gear every year. They were willing to pay for progress. They were the most valuable customers in the running category, but no brand catered to them exclusively. That was the moment where it all made sense to us. We would disrupt running with innovation, and we would only sell at the premium end of the market.”
Critically, On consistently acts in a way that reinforces it’s premium brand image. To paraphrase management, operating in that manner is simple in principle, yet demanding in practice, and powerful because it compounds.
As management noted, On has the industry’s lowest discount rates and the highest average selling prices (“since 2023, we have taken ASPs from $145 to $170”). On the latter figure, they also noted their U.S. wholesale ASPs are ~40% higher than their peer average. In a more mature category for On like Running, the company’s pricing architecture has evolved to cover a broader range of price points, with success driving “better” / “best” SKU adoption:
“Generally speaking, we will not take prices down. That is off the table. But we have different playbooks of price points we design to. In performance, what we’ve seen is that the aperture is opening up. For example, we’ve seen a really strong response to Cloudmonster 3, which comes in three versions - regular Cloudmonster [~$190], Cloudmonster Hyper [~$220] and LightSpray Cloudmonster Hyper [~$280]. A very large share of Monster, 40% - 50%, is from those higher-priced versions, much more than we expected. We’ve actually been chasing the units to go after that… In performance, we want to open up the aperture: an initial price point probably around $160, then something at $200+, and then something that’s closer to $300.”
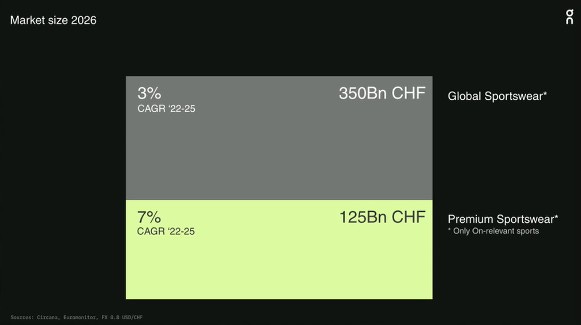
Naturally, this strategy has its limitations, particularly in terms of market size. As quantified at Investor Day, the premium sportswear segment is ~$150 billion (125 billion CHF), and it accounts for roughly one-third of the global sportswear market. Said differently, there’s the other ~65% of the market that On does not – and per management’s vision, will never – compete within.
When asked about the trade-off that this will present over time, particularly if the brand aspires to sustain outsized topline growth in the decade ahead, co-CEO Caspar Coppetti said the following:
“I just don’t think that holds true [tight growth / margin trade-off]. The premium playbook has been applied in other industries – say, consumer electronics, what Apple has done. They are high margin, the highest price point, and the highest market share. What it comes down to, and I think it’s what your question is leading to, is discipline. We’re educating our consumer not to expect a sale from us, and we’re going to fulfill that promise. As long as we stay the course on the premium playbook, there isn’t an either / or tension; it’s actually reinforcing.” (And when it goes wrong, losing control of promotional intensity creates material brand risk, as seen at Nike under John Donahoe.)
As I discussed in July, I think On management deserves a lot of credit for continuing to do an effective job of nurturing the long-term development of their premium sports brand, while also delivering strong financials. In the face of a near-term environment with heightened competitive intensity and some unforeseen external developments (U.S. tariffs), they’ve delivered compelling results that exceeded the trajectory envisioned at their 2023 Investor Day.
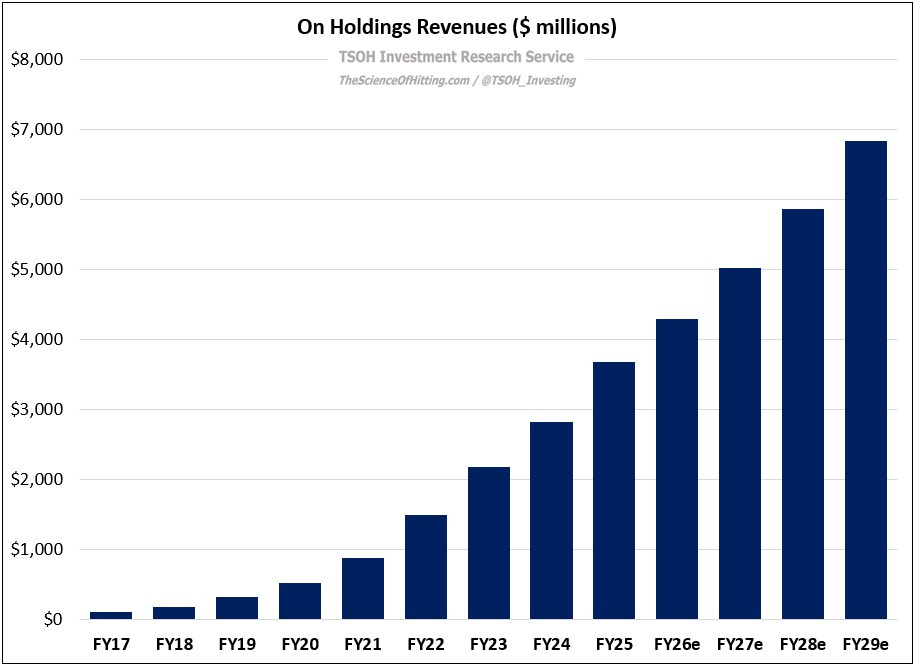
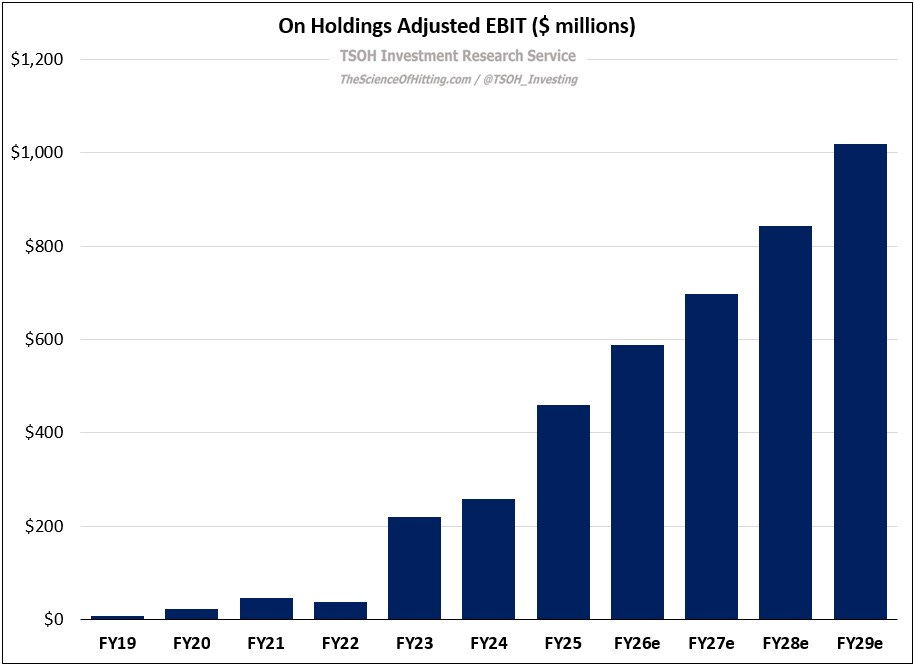
From a financial perspective, the past three years (FY23 – FY26e) have been quite rewarding: a mid-20’s revenue CAGR, with nearly 500 basis points of adjusted EBITDA margin expansion. The vision for the next three years, as outlined at Investor Day, is similarly impressive: high-teens annualized constant currency net sales growth and adjusted EBITDA margins expanding another ~200 basis points to at least 22%. In addition, the Board authorized an inaugural share repurchase program, for up to $1 billion through the end of 2029, which is equal to ~10% of the market cap. (The following charts are in dollars; as noted at Investor Day, management is preparing to move to U.S. dollar reporting in 2027, which aligns with their share price currency.)
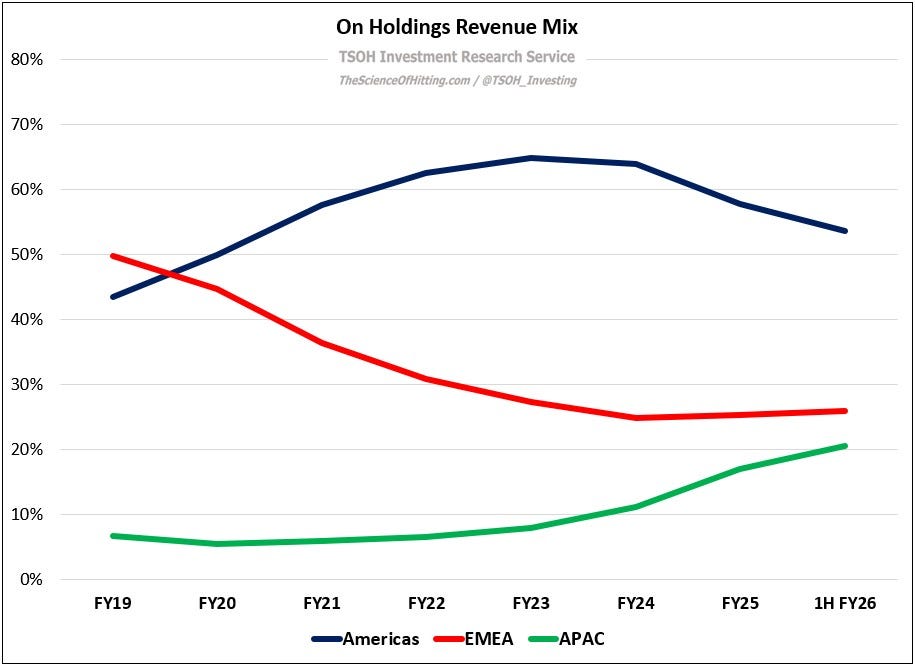
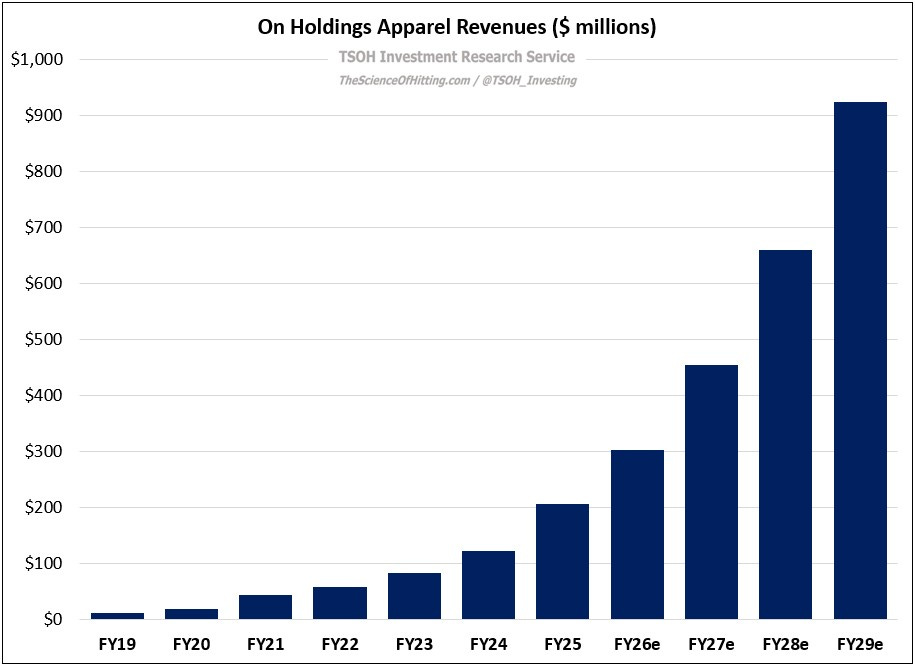
On’s growth strategy includes a few key levers: first, broad global expansion, with low-teens growth in America outpaced by ~20%+ growth in EMEA and APAC; second, a significant expansion of their Apparel business, with revenues climbing from ~$200 million in FY25 to ~$900 million in FY29e; and third, the Lifestyle business, led by Cloudtilt (“Cloudtilt is one of the industry’s fastest-growing sneaker franchises, and the precursor of more to come”).
As noted earlier, Mr. Market’s optimism has faded over the past few years, with ONON closing on Friday at ~$30 per share – down ~50% from the early 2025 highs. With ~336 million diluted shares, the company has a market cap of ~$10 billion and an enterprise value of ~$8.6 billion. As you can see below, the EV/EBIT multiple Mr. Market has typically deemed appropriate for On was 30x, 40x, or even 60x; today, it trades at ~14x FY26e EV/EBIT. (Relative to the ~$1 billion of FY29e EBIT shown earlier, the stock is at ~8.5x EV/EBIT.)
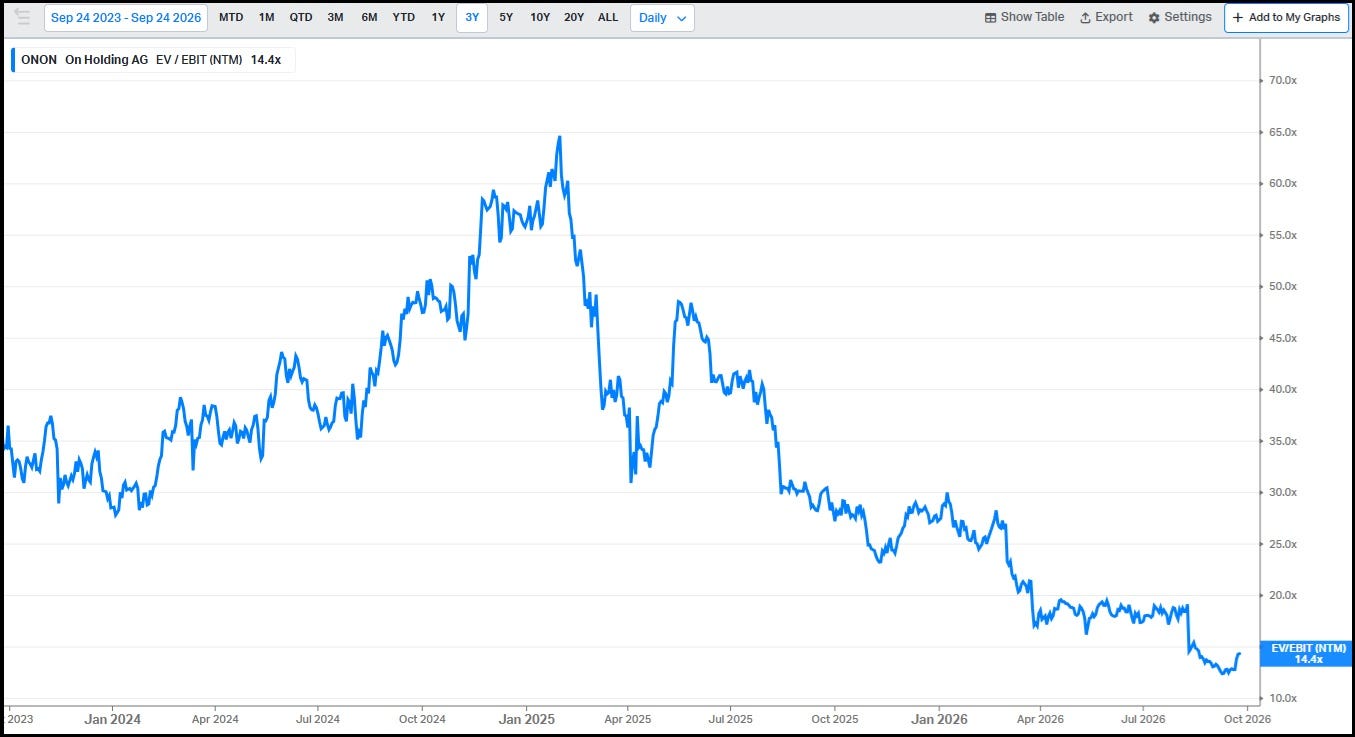
Mr. Market is suddenly feeling much less optimistic, a statement that applies to peers like Deckers and Nike, as well as major retail partners like Dick’s Sporting Goods. In my view, while I certainly appreciate that more cautious sentiment given On’s growing size and the constraints of their premium-only model, I think the runway for this business will extend well beyond what the valuation now implies. This brand has staying power and room for growth.
Conclusion
As noted in the opening quote, I came into Investor Day with an openness to changing my conclusion depending on the clarity of the vision presented. Personally, I think management hit all the right notes, and I’m confident they will continue to etch out a unique path by remaining committed to their premium playbook. In addition, the stock took on further water in recent months amidst broader industry pressures, pushing On’s valuation lower.
In summary, I think now is a good time to initiate an ONON position.
I’ll send the portfolio change email before the market opens (at 9am ET).
NOTE - This is not investment advice. Do your own due diligence.
I make no representation, warranty, or undertaking, express or implied, as to the accuracy, reliability, completeness, or reasonableness of the information presented in this report. Assumptions, opinions, and estimates expressed in this report constitute my judgment as of the date thereof and are subject to change without notice. Projections are based on a number of assumptions, and there is no guarantee that they will be achieved. TSOH Investment Research is not acting as your advisor or in any fiduciary capacity.