Review all prior FEVR research and portfolio changes on the TSOH website
From “Fever-Tree: A Pivotal Moment” (March 2026):
“Group results have been defined by headwinds in UK Tonics – a business which accounted for more than 50% of FY18 revenues, and which declined at a high-single digit annualized rate over the next seven years. The good news is that UK Tonics have since shrunk to only ~20% of Fever-Tree’s revenue base. The rest of the pie is a ~£300 million business that grew at a mid-teens annualized clip over the past seven years, primarily due to the expansion of the non-Tonics range – starting with gingers, followed by premium sodas / soft drinks, cocktail mixers, and non-alc RTD’s. My investment is a bet on their long-term runway in the other ~80%.”
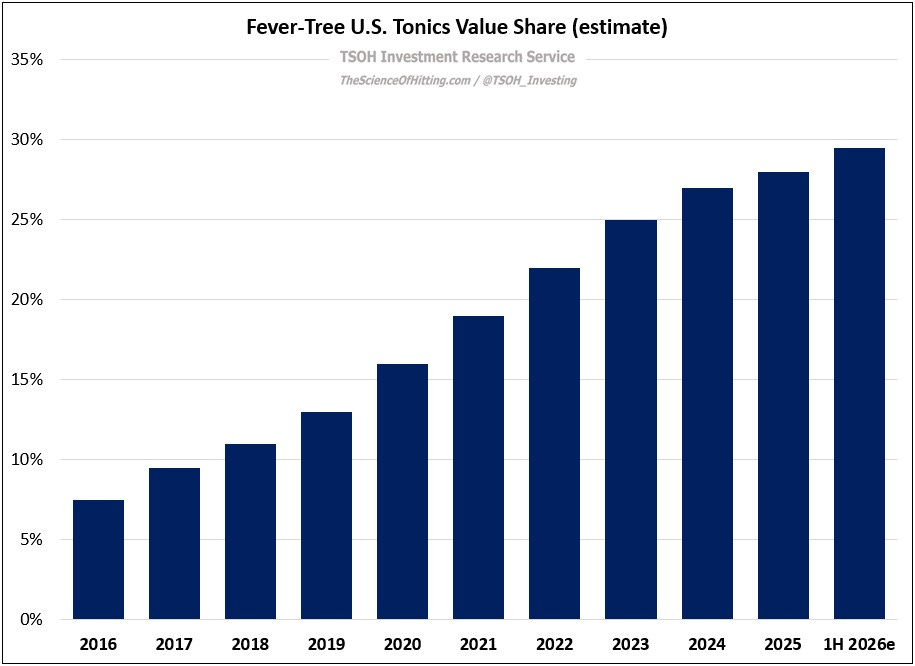
Fever-Tree’s long-term value outside of its home market will largely be determined by the evolution of their U.S. business, managed in partnership with Molson Coors. In 1H FY26, the U.S. region delivered low-double digit constant currency revenue growth, with the brand’s retail value ($) share in ginger beers and tonics reaching record highs. As noted on the call, growth accelerated through the period, with Off-Trade sales growing 6% in Q1 and 11% in Q2, and with that growth rate climbing to the mid-teens in July and August (the first two months of Q3 FY26). I think this is the early innings: an acceleration to high-teens U.S. growth should materialize in 2H 2026, and I expect at least mid-teens p.a. growth to persist in the years ahead. (CFO Andy Branchflower: “You’re seeing a combined benefit of more doors, more shelf space, and an improving rate of sale… Each month, it’s building.”)