Note: Review 5+ years of META research and trades on the TSOH website.
From “Meta: In Limbo” (August 2026):
“While I remain confident about the long-term future in Meta’s core business, and while I think that the current valuation is at least reasonable, I believe management’s likely course of action in the years ahead has greatly changed the range of possible outcomes for this business, particularly if they struggle to close the gap with MSL’s leading competitors. Here’s one data point to help contextualize how the range of outcomes is changing: a year ago, Meta had ~$28 billion of non-cancelable contractual commitments, primarily related to investments in servers and network infrastructure, with the majority to be realized by yearend 2025 [within six months]. One year later, Meta now has ~$349 billion of non-cancelable contractual commitments, with more than 60% of those commitments (>$200 billion) coming due in 2028 or later.”
Developments over the past three months neatly frame the Meta debate: while there are encouraging signs of progress in the core business, along with green shoots from emerging opportunities, that all comes with the asterisk of how much is being spent / invested to get there – and, critically, uncertainty on their willingness to adjust if things started to go sideways.
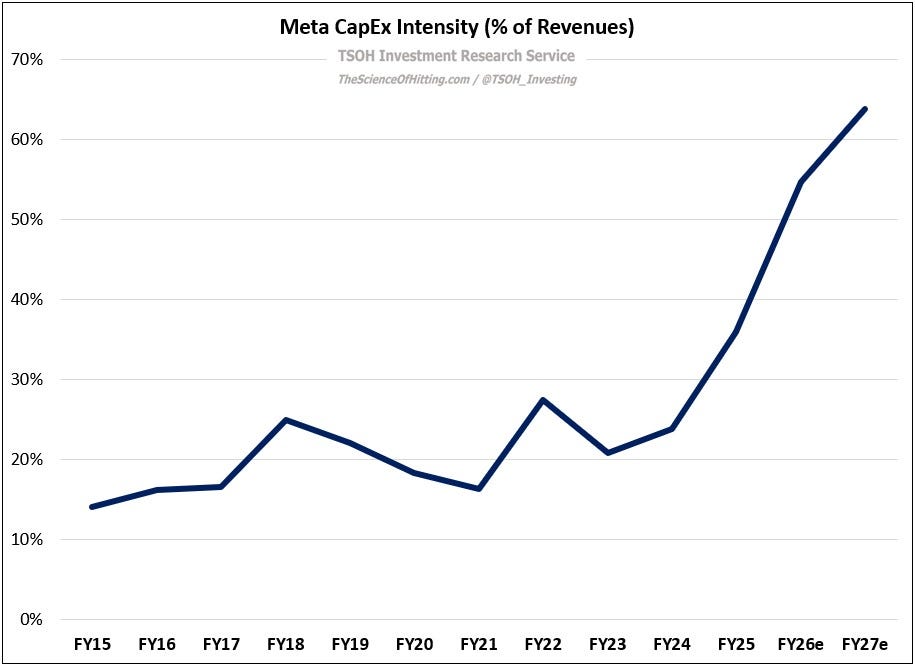
First, an update on the above figures: the value of non-cancelable contractual commitments increased >$100 billion over the past 90 days, to ~$455 billion. As it relates to capital expenditures, management expects FY26e spending to nearly double YoY, to ~$140 billion (original FY26e CapEx guidance, set alongside the Q4 FY25 results, was ~$125 billion). This will result in FY26e CapEx intensity of ~55%, with yet another leg higher likely coming in FY27e.
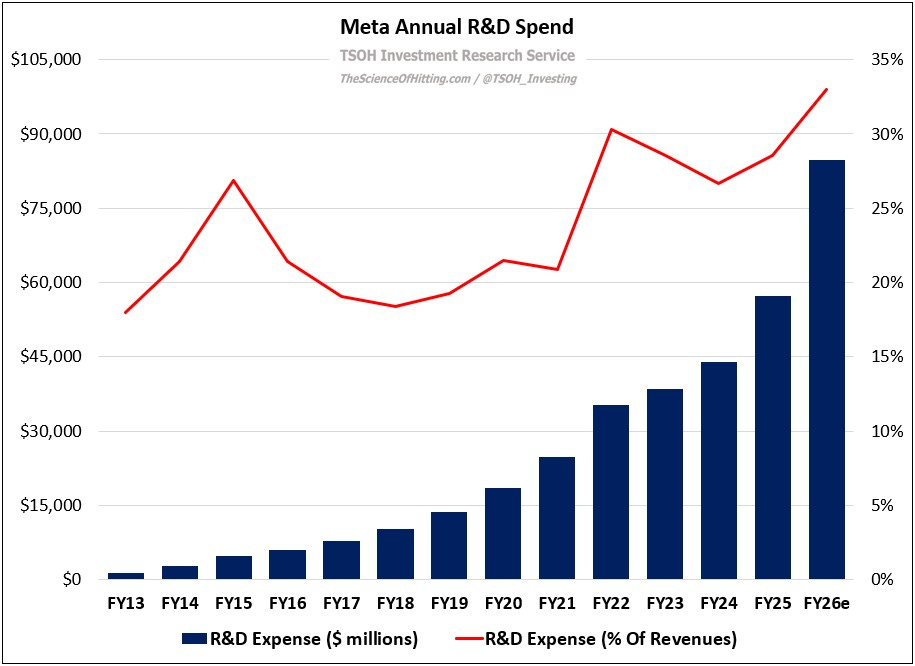
In addition to depreciation expense, other costs are skyrocketing higher. For example, research and development expense is on track to increase by nearly 50% this year, to ~$85 billion. As a result, it will be equal to ~33% of revenues, or ~1,000 basis points higher than the trailing ten-year average.
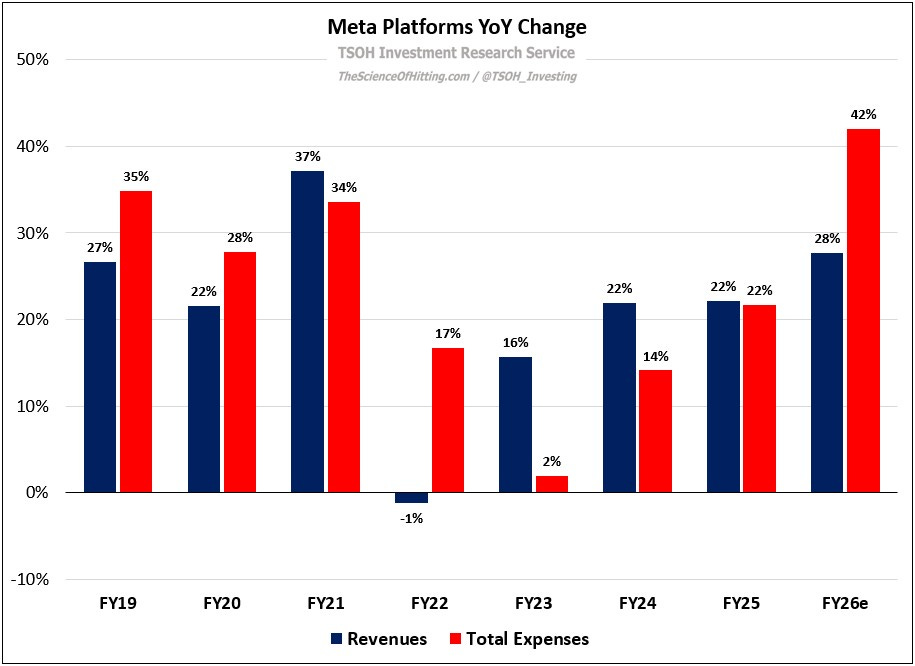
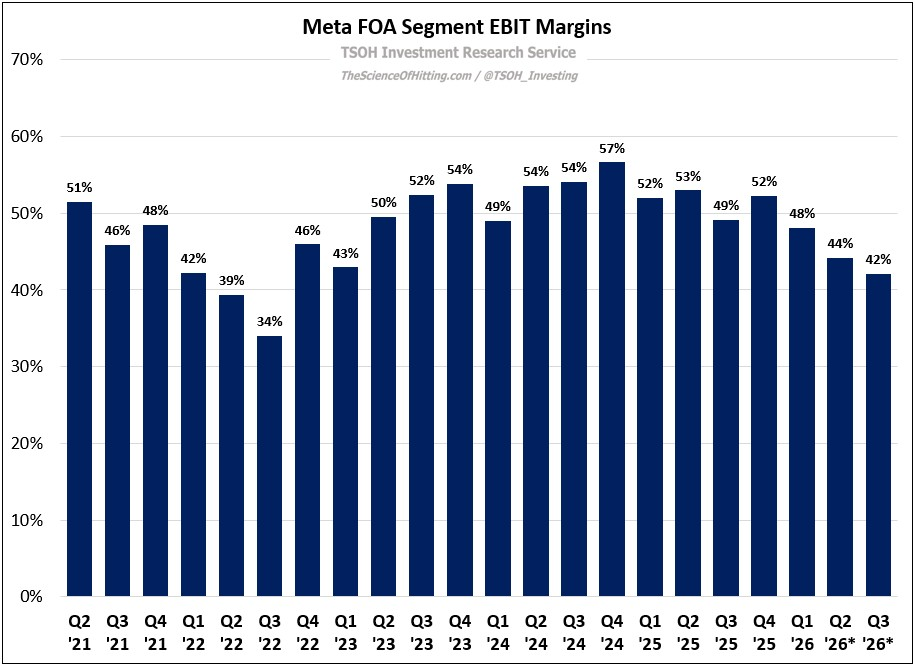
Altogether, you have a business on track for ~42% total expense growth in FY26e, to ~$167 billion (adjusted for the nearly $10 billion charge from the AG settlement related to teen mental health and social media; I remain cautious about the long-term cost of legal and regulatory risks). This is their highest adjusted expense growth (%) in eight years, and it’s well ahead of expected FY26 revenue growth. The result is persistent margin pressure, with Q3 FY26 FOA segment adjusted EBIT margins down ~700 basis points YoY.