

In the conclusion of the Airbnb deep dive (“Belonging Anywhere”), which was published for TSOH subscribers in September 2021, I wrote the following:
But even if you agree on the business, what about the stock?
Frankly, I have a tough time getting close to $110 billion.
First, let’s start with GBV, which was $38 billion in 2019. Assuming that 2021 GBV comes in at around $45 billion (implies +20% vs 2019), with low 20’s annualized growth, on average, in years 2022 and beyond (compared to +38% in 2018 and +33% in 2019), GBV will reach $100 billion by 2025 or 2026. Assuming the take rate is unchanged, that would result in about $14 billion in service fees (revenues). Even if we assume significant progress on the company’s long-term financial targets, with EBIT margins climbing to 20% - 25%, that leaves us with run rate operating income of roughly $3 billion (call it $2.5 billion after-tax). Relative to today’s $110 billion market cap, which will bleed higher by a few percentage points per year even if the stock price doesn’t change as a result of significant equity issuance (SBC), I’m not so sure we’re getting a reasonable price here, even if the future looks bright.
At a minimum, an investment in Airbnb at today’s valuation requires a view on outsized GBV growth beyond $100 billion and / or normalized profit margins in excess of management’s long-term guidance. I do not feel comfortable making either of those assumptions at this time.
While I respect what the company has built over the past 14 years, and believe it will become a much larger business over the next decade, Mr. Market’s ask is a bridge too far for me. In the future, if I’m given the chance to buy this business at something closer to 20x - 30x normalized 2026e earnings (call it $50 billion to $75 billion), that would pique my interest.
Over the ensuing 14 months, a lot has changed - most notably the ~40% decline in the company’s stock price. Today, the business has a market cap of ~$65 billion, inside the range of what I considered to be a reasonable valuation back in September 2021. In addition to the change in the stock price, there has been some material changes in the underlying business.
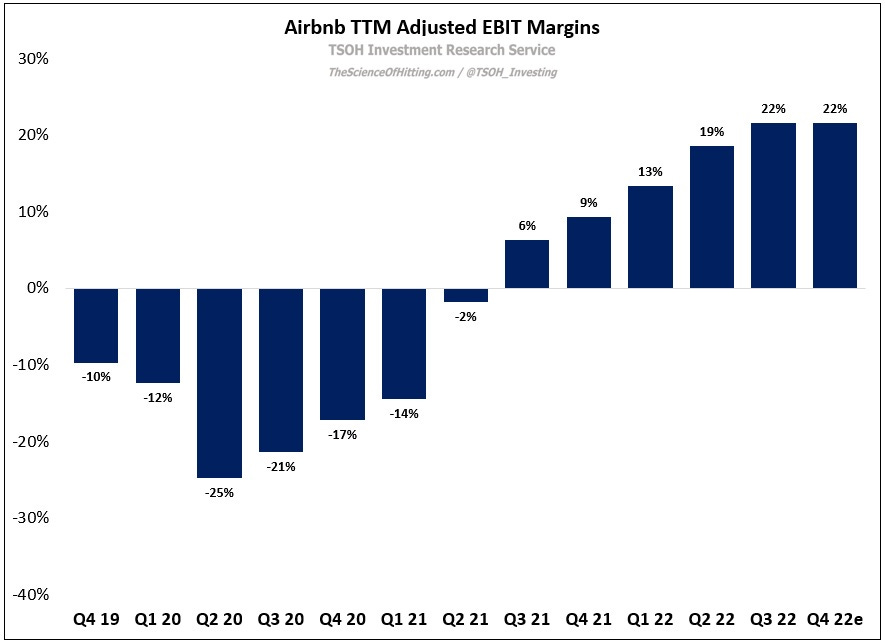
The strength in Nights & Experiences (N&E) booked and average daily rates (ADR’s) has led to meaningful revenue growth. In addition, significant improvement in the expense structure, most notably as it relates to performance marketing spend, has led to ~3,200 basis points of TTM adjusted operating margin expansion compared to pre-pandemic levels (in 2022e, Airbnb will likely generate ~$1.8 billion of operating income).
Next week, I will provide my updated thoughts on the Airbnb thesis, along with my investment decision (initiate a position or stay on the sidelines).
Before doing so, I wanted to share some additional thoughts on the business with you. This morning, I removed the paywall on “Growth & Profitability At Scale”, the ABNB update published in August 2022 (here’s the link).
In the post, I discuss some of the key considerations for the long-term investment thesis (ADR trends, the sustainability of long-term stays, normalized margins, etc.). For complete access to the TSOH Investment Research service, including next week’s Airbnb update, subscribe below.
As always, thank you for your time and for considering this research service.
NOTE - This is not investment advice. Do your own due diligence. I make no representation, warranty or undertaking, express or implied, as to the accuracy, reliability, completeness, or reasonableness of the information contained in this report. Any assumptions, opinions and estimates expressed in this report constitute my judgment as of the date thereof and is subject to change without notice. Any projections contained in the report are based on a number of assumptions as to market conditions. There is no guarantee that projected outcomes will be achieved. The TSOH Investment Research Service is not acting as your financial advisor or in any fiduciary capacity.