

From “Constellation Brands: Opportunity Brewing?” (September 2025):
“As my coverage of companies in the alcohol industry has expanded, I’ve developed more appreciation for changing competitive dynamics and shifting consumer preferences, along with how different companies are responding to those developments. One consistent theme is the critical importance of capital allocation and M&A. I’m wary of those engaging in a seemingly endless number of divestitures and acquisitions, with little reason to believe this activity has, or will, generate material value for owners (see Brown-Forman). Securing the U.S. rights to Modelo, Corona, and other Mexican beer brands was clearly a fantastic deal by Constellation – but more recent examples in cannabis and craft beer led to significant value destruction… My focus as I learn more about STZ will be to develop a clearer sense for future capital allocation decisions. To give a recent example, I’d prefer fewer deals like Sea Smoke; to me, it signals a lack of focus on what moves the needle.”
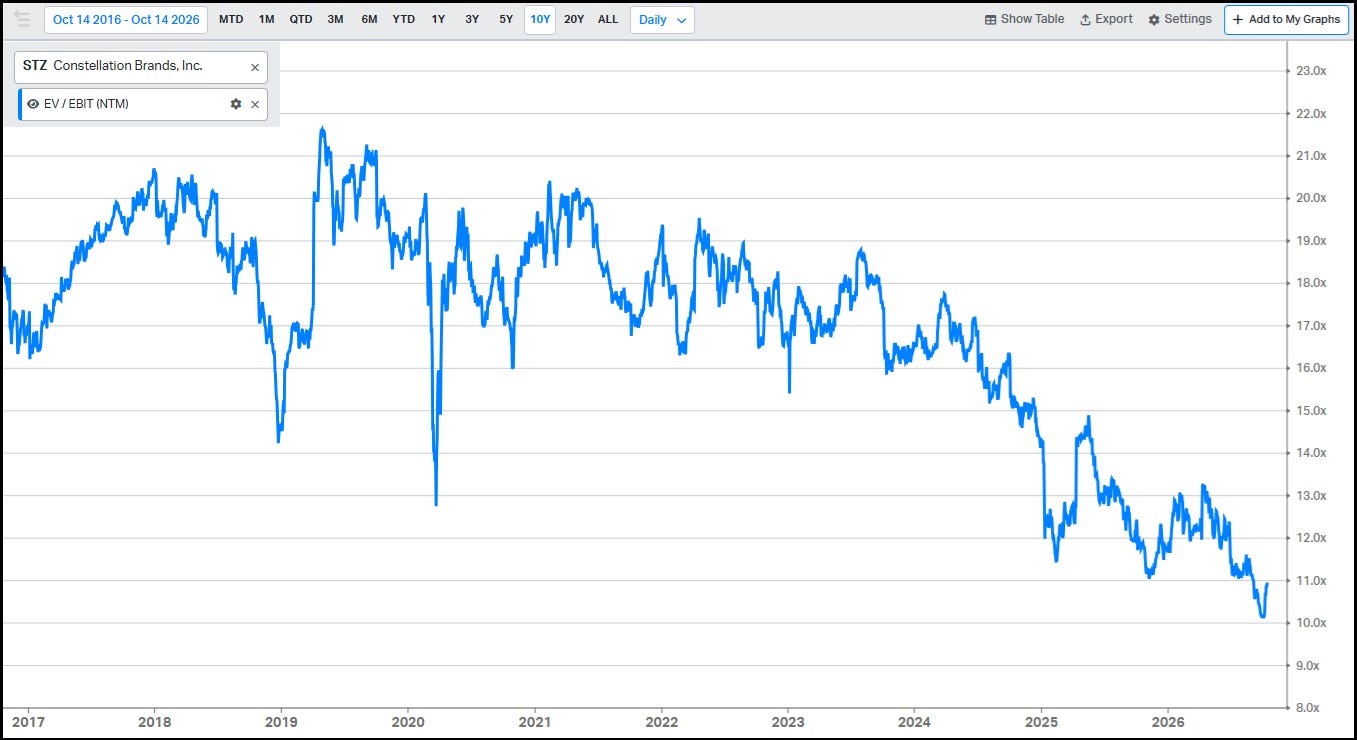
When that initiation was published, STZ was a ~$140 stock trading at ~13x NTM EV/EBIT – a meaningful reduction from the multiple Mr. Market had previously deemed appropriate for the business. It has remained challenged subsequently: as of Wednesday’s close, STZ is a ~$127 stock trading at ~11x NTM EV/EBIT. It was a “cheap” stock a year ago, and it’s a bit cheaper today.
And yet, while the stock price hasn’t cooperated for the past 5+ years, I think that the recent business results are presenting reason for some optimism.